Mental Accounting Biases in Corporate Decision-Making: Evidence from Indian Managers
DOI:
https://doi.org/10.31033/IJEMR/16.5.2026.1949Keywords:
Mental Accounting, Behavioural Finance, Corporate Decision-Making, Indian Managers, Managerial BiasAbstract
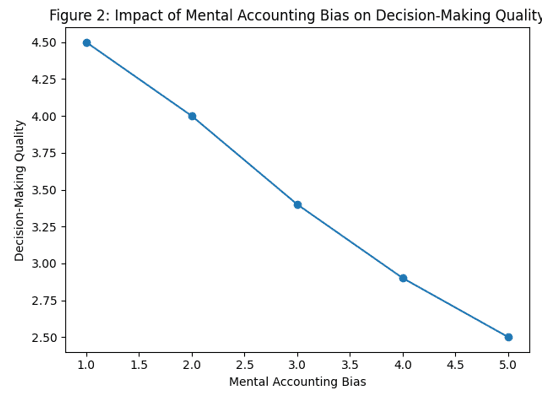
Mental accounting describes the manner in which individuals mentally structure and evaluate financial information by assigning monetary outcomes to separate cognitive categories. Although this behavioural tendency has received considerable attention in studies on individual investors, its relevance in organizational decision-making has not been adequately examined, particularly within emerging market contexts. This study explores the existence and influence of mental accounting biases among Indian managers, with specific reference to budgeting, investment evaluation, and resource allocation decisions. Adopting a quantitative survey-based approach, primary data were gathered from managerial professionals representing diverse sectors in India. Statistical tools such as descriptive analysis, reliability testing, correlation, and regression were employed to examine the association between mental accounting bias and managerial decision-making quality. The results indicate that managers frequently engage in mental compartmentalization of financial decisions, even in the presence of formal controls, resulting in departures from optimal decision outcomes. The study extends behavioural corporate finance literature by contextualizing mental accounting within managerial roles and offers governance-oriented insights for improving decision-making effectiveness.
Downloads
References
Thaler, R. H. (1985). Mental accounting and consumer choice. Marketing Science, 4(3), 199–214.
Simon, H. A. (1957). Administrative behavior. Free Press.
Baker, M., & Wurgler, J. (2013). Behavioral corporate finance: An updated survey.
Thaler, R. H. (2018). Misbehaving: The making of behavioral economics. New York: W. W. Norton & Company.
Baker, M., Ruback, R. S., & Wurgler, J. (2022). Behavioral corporate finance: A survey. Annual Review of Financial Economics, 14, 1–28. https://doi.org/10.1146/annurev-financial-110921-023646
Malmendier, U., Tate, G., & Yan, J. (2020). Managerial beliefs and corporate financial policies. Journal of Finance, 75(3), 1209–1250. https://doi.org/10.1111/jofi.12878
Shefrin, H. (2020). Behavioral risk management: Managing the psychology that drives decisions and influences operational risk. Palgrave Macmillan.
Heath, C., & Soll, J. B. (2019). Mental budgeting and consumer decisions. Journal of Consumer Research, 46(3), 567–585. https://doi.org/10.1093/jcr/ucz020
Goyal, K. A., & Kumar, S. (2021). Behavioral biases in managerial decision-making: Evidence from emerging markets. Global Business Review, 22(6), 1447–1464. https://doi.org/10.1177/0972150920929902
Gupta, K., & Ahmed, S. (2022). Cognitive biases and managerial decision-making in Indian firms. Indian Journal of Corporate Governance, 15(2), 173–191.
Published
How to Cite
Issue
Section
License
Copyright (c) 2026 Sruthi S G, Irshad V

This work is licensed under a Creative Commons Attribution 4.0 International License.
Research Articles in 'International Journal of Engineering and Management Research' are Open Access articles published under the Creative Commons CC BY License Creative Commons Attribution 4.0 International License http://creativecommons.org/licenses/by/4.0/. This license allows you to share – copy and redistribute the material in any medium or format. Adapt – remix, transform, and build upon the material for any purpose, even commercially.


